
From cost centre to revenue node
The old model and the new one
| The old model | The Urban Computer | |
|---|---|---|
| Funding | Public capital, paid by taxpayers | Private capital in a node SPV, with developers, investors and partners |
| Return | None: the junction is a cost | Colocation rent from the compute, plus other income |
| Maintenance | An ongoing public liability | Funded by the asset over its life |
| Congestion | Managed, never removed | Removed at source |
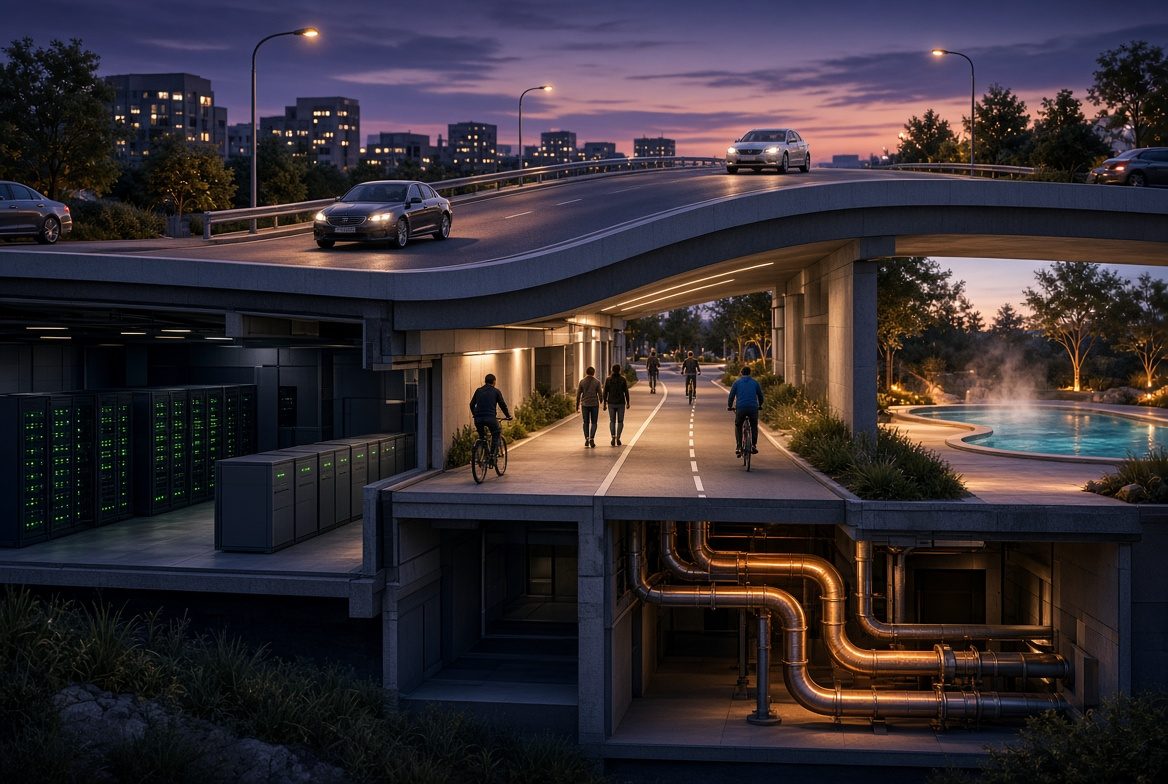
| Land | A junction and nothing more | Innerspace for compute, storage and heat, at no new land cost |
Where the income comes from
Compute is the anchor
Colocation is the anchor. Around it, a node can earn from battery storage and grid services, EV charging, heat supplied to nearby buildings, ground rent, and civic and commercial space, depending on the site. In the base case, these cover the node’s operating costs, so net operating income stays at about €3M a year.
Three operating models
One structure, three levels of risk
Landlord
The node provides Colocation: space, power, cooling and connectivity, and the tenant brings the hardware. No exposure to chip prices.
HaaS Lease
The node leases hardware from a financing partner and sells capacity. Higher income, with chip risk held by the lessor. Modelled at up to ~€12M a year per MW in our base case.
HaaS Own
The node owns its hardware through vendor financing, for the highest income of the three, refreshing racks over time from revenue.
Each node is held in its own SPV, so developers, councils, insurers and investors can take equity alongside us and choose the model that fits their appetite for risk.
Who gets what
Different partners, one asset
| Partner | What they gain |
|---|---|
| Developer | An access junction that earns instead of costing, and equity in the node |
| Council | A free-flow junction and a daylit crossing, with no public capital asked |
| Compute buyer | Inference capacity close to its users |
| Infrastructure fund | A long-life asset with recurring income |
| Energy partner | Storage and charging on an already-consented urban site |
| Insurer | A stake in fewer conflict points and fewer claims |
Infrastructure that pays for itself is not a new idea. It has simply never been applied to junctions, until now.